Blog· November 2, 2026
Field notes: the account we almost wrote off until the fourth quarter proved us wrong
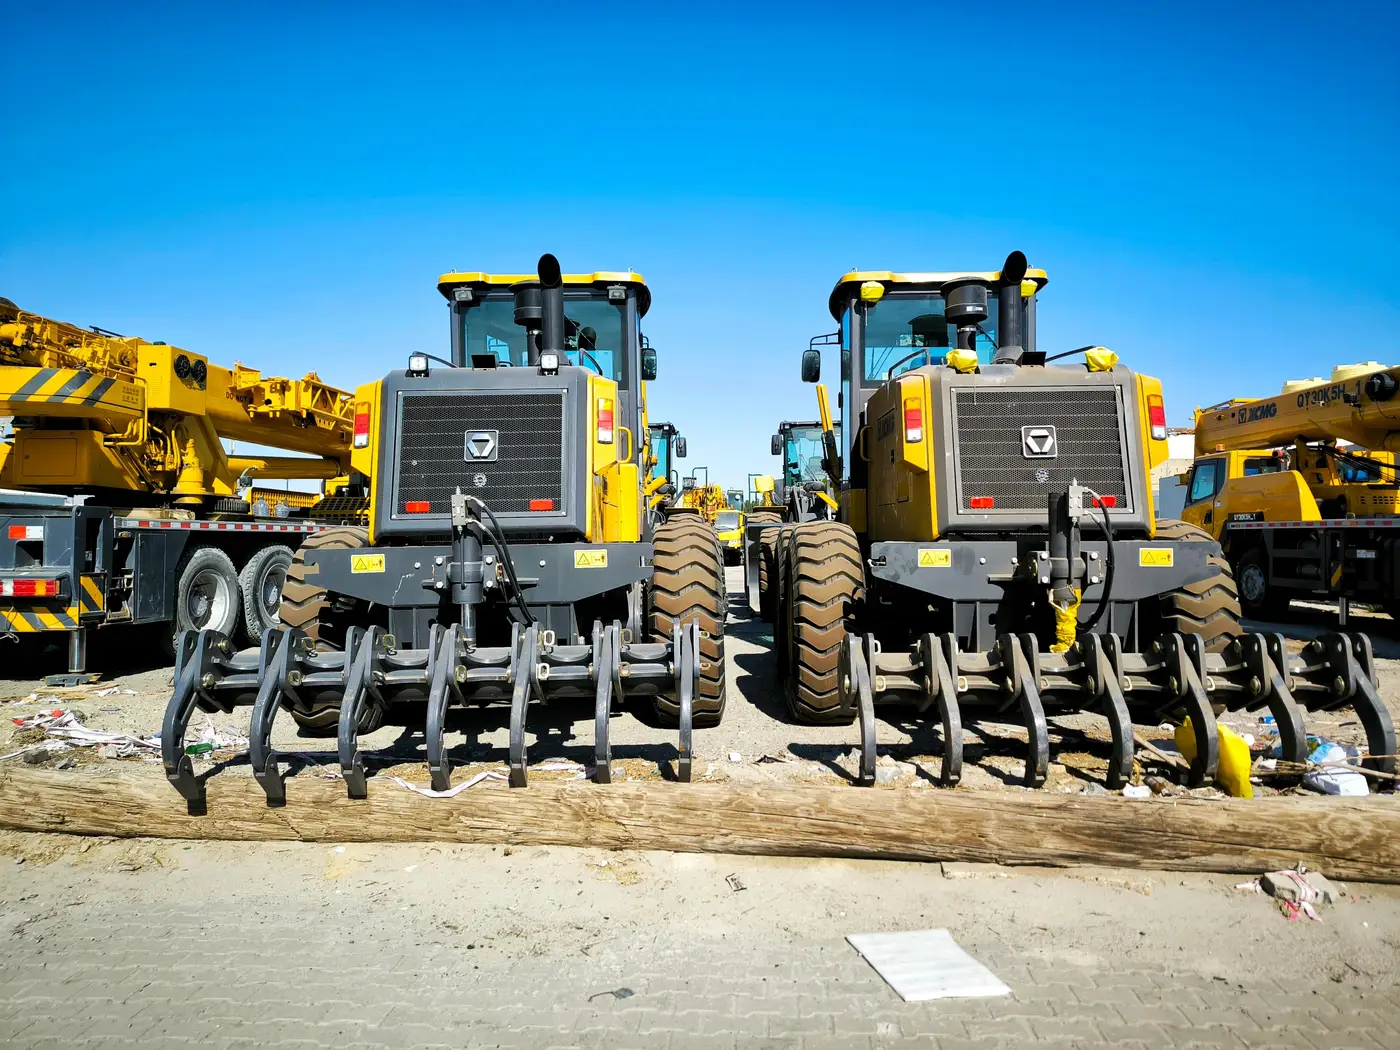
We almost pulled this account off the watch list in Q3.
Three quarters running, the count on this yard had gone the wrong way. Our iron down, a competitor's up, and not by a little. Q1 showed twenty-two units of ours against eleven of theirs. By Q3 it was sixteen and nineteen. Flip a share chart like that in front of a regional manager and you get the same question every time: do we pull a rep in, or do we just write the account down as lost and spend the travel budget somewhere the trend isn't already decided.
The instinct, especially by quarter three of a slide, is to call it. Three data points in a row feels like a pattern, and a pattern feels like a verdict. We'd seen this shape before on other lots: a rival wins a big rental order, the yard fills with their paint for a year or two, and the account quietly becomes theirs. Nobody signs a press release when that happens. The count just keeps drifting until one day the yard that used to be split fifty-fifty is their yard with a few of ours left over for parts compatibility.
So we almost did it. Then Q4 came back and the count was twenty-four and fourteen. Not a blip, a swing. More of ours than we'd seen in a year, and a real drop in theirs.
What actually happened, we found out later through the rep, had nothing to do with brand preference shifting back our way. The competitor had a floor plan problem. Their dealer financing arrangement on a batch of rental units came up for renewal at a bad time, the units got pulled back to a regional yard for reallocation, and our customer's lot simply had empty pads to fill. We happened to be the ones with available inventory and a rep who called that week. None of that shows up in a brand-loyalty survey. It shows up as iron parked on a lot, and it shows up on the next count.
Here's the part worth sitting with: if we'd stopped reading after Q3, we'd have written the account off right before the quarter that mattered most. A single read, even three single reads stacked in a row, told us a story that the next ninety days contradicted completely. The three-quarter slide was real. It just wasn't the whole picture, and it wasn't where the account was headed.
This is the argument for cadence over conviction. A snapshot tells you where the yard stands today, and today is always a little bit of an accident: a financing hiccup, a rental return, a job that wrapped early and freed up a pad. A trend built from the same count taken the same way, quarter after quarter, tells you something closer to the truth, which is that yards move in both directions for reasons that have nothing to do with the sales pitch anyone's giving. You don't get to see that shape from one drive-by, and you don't get to see it from three, if those three happen to land on the same side of a cycle.
We track this account the same way now that we track every account on the list: a repeatable quarterly read, not a judgment call made off the last visit. That's the whole discipline behind the way we run this, and it's the reason we built a standing count across every yard on the account list instead of relying on a rep's memory of what he saw driving past the gate last spring.
If you've got an account you're about to write off on the strength of two or three bad quarters, give it one more read before you move the budget.